

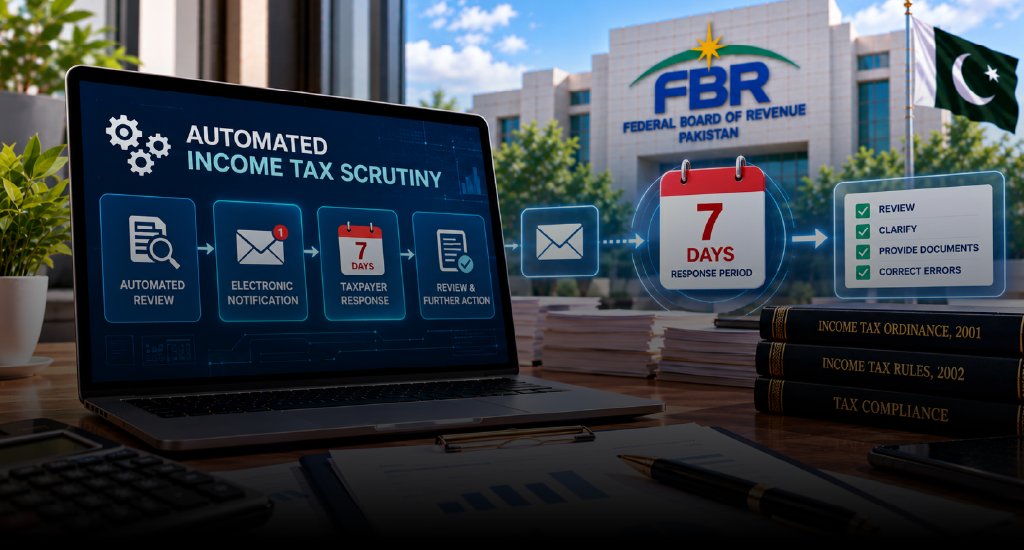
The Federal Board of Revenue (FBR) has proposed a new automated income tax scrutiny mechanism to identify errors, legal issues and discrepancies in income tax returns before formal legal or penal proceedings are initiated. Under the proposed framework, taxpayers would receive electronic notifications and have an opportunity to clarify or correct identified issues within a specified response period of at least seven days.
The proposal is part of Pakistan’s broader move towards technology-driven tax administration, automated data analysis and improved tax compliance. For individuals, businesses and corporate taxpayers, understanding this proposed system is essential to managing tax obligations and responding to potential discrepancies.
What Is the Proposed FBR Automated Income Tax Scrutiny System?
The FBR has proposed amendments to the Income Tax Rules, 2002, through a new Rule 38B concerning the electronic scrutiny and intimation of issues detected by an automated system.
The proposed mechanism would use computerized tools, including customer relationship management (CRM) systems, to examine income tax returns and identify potential factual or legal errors.
The system would process returns furnished under Section 120(2A) of the Income Tax Ordinance, 2001, and may generate electronic advice or advance intimation through the FBR’s IRIS portal.
The primary objective is to give taxpayers an opportunity to clarify discrepancies, correct errors or take appropriate corrective action before further proceedings are considered.
Important: The income tax scrutiny mechanism described here was proposed through draft rules. Taxpayers should verify the applicable rules and their current legal status before acting on the proposal.
How Will Automated Income Tax Scrutiny Work?
Under the proposed framework, the process would involve several stages.
1. Automated Review of Income Tax Returns
The computerized system would analyse income tax returns and cross-match information against other data available to the tax authorities.
The system could identify inconsistencies, factual mistakes, legal issues or other discrepancies requiring clarification.
2. Electronic Notification Through IRIS
Where the system identifies a potential issue, an online advice or advance intimation may be issued through IRIS. The relevant Inland Revenue officer having jurisdiction over the taxpayer may also issue the notification generated through the system.
The notification would identify the discrepancy and provide the taxpayer with an opportunity to respond.
3. Minimum Seven-Day Response Period
One of the most important features of the proposal is the requirement to provide taxpayers with at least seven days to respond to the electronic intimation.
During this period, taxpayers would be able to:
- Explain the circumstances surrounding the identified discrepancy.
- Provide supporting documents and relevant information.
- Correct factual or computational errors where appropriate.
- Take other corrective measures to address the issue.
The actual deadline would be specified in the electronic notification. Taxpayers should carefully review each notice rather than assume that every case will have an identical deadline.
4. Reminder If No Response Is Received
If a taxpayer does not respond within the specified period, the proposed rules provide for a reminder.
The reminder would allow a further response period of at least seven days, giving the taxpayer another opportunity to address the issue.
However, taxpayers should not treat the reminder as a reason to ignore the original notice. Responding promptly remains the safer approach.
5. Review by the Relevant Inland Revenue Officer
The proposed system would record identified discrepancies, notifications issued and responses received.
This information would be communicated to the relevant Inland Revenue officer and recorded through a system dashboard.
The officer would examine the taxpayer’s response—or the absence of a response—and determine whether further action is necessary under the applicable provisions of the Income Tax Ordinance, 2001, and relevant rules.
What Types of Tax Discrepancies Could Be Identified?
Automated scrutiny and cross-matching may help identify different types of potential inconsistencies in tax returns. Depending on the information available and the system’s configuration, these could include:
Income Reporting Differences
Declared income may require clarification where it appears inconsistent with other information available to the tax authorities.
Incorrect Deductions or Tax Credits
Claims for deductions, allowances or tax credits may be flagged if the information in the return suggests an inconsistency or requires verification.
Tax Calculation Errors
Computational mistakes or inconsistencies in the calculation of taxable income and tax payable may require correction or explanation.
Inconsistencies in Financial Information
Differences between reported figures and other available financial information may prompt the FBR to request supporting documents or clarification.
Missing or Inconsistent Information
Incomplete declarations or conflicting entries within a tax return may also require attention.
An automated flag does not, by itself, establish tax evasion or automatically prove that a taxpayer has violated the law. The underlying facts, supporting evidence and applicable legal provisions must be considered.
Does an Automated Scrutiny Notice Mean a Penalty Will Be Imposed?
No. Under the proposed mechanism, the purpose of advance electronic intimation is to give taxpayers an opportunity to clarify or correct identified issues before formal legal or penal action is initiated.
Receiving a notification should therefore be treated as an opportunity to review the relevant tax return and provide a properly supported response.
The ultimate outcome would depend on the facts of the case, the taxpayer’s explanation, the supporting documents and the applicable law. Where a discrepancy remains unresolved, the relevant Inland Revenue officer may consider further action under the applicable legal framework.
Taxpayers should not assume that every system-generated notification will lead to an assessment, penalty or other enforcement action.
How Should Taxpayers Prepare for the Seven-Day Response Period?
A short response period can create challenges for individuals and businesses that do not maintain organized financial records. Taxpayers should consider the following steps to improve their readiness.
1. Review the Tax Return Carefully
Check the information reported in the relevant return, including income, expenses, deductions, tax credits and tax payments.
2. Keep Supporting Documents Organized
Maintain relevant invoices, bank statements, financial statements, withholding tax certificates, payroll records and other supporting documents.
3. Monitor the IRIS Portal
Check the FBR’s IRIS portal regularly for electronic notifications and other tax-related communications.
4. Identify the Exact Discrepancy
Read the notification carefully to understand what information has been questioned and which tax year or transaction is involved.
5. Prepare a Clear and Evidence-Based Response
Provide a direct explanation supported by relevant records. If a genuine error has occurred, assess the appropriate corrective action under the applicable law.
6. Seek Professional Tax Advice When Needed
Where the issue involves complex transactions, disputed deductions, unexplained income or potential penalties, professional guidance can help ensure that the response is accurate and legally appropriate.
What Does This Proposal Mean for Businesses in Pakistan?
The proposed automated income tax scrutiny system reinforces the importance of accurate reporting and consistent financial records.
Businesses should ensure that their accounting systems, financial statements, tax returns and supporting documentation are properly maintained and reconciled.
For companies with multiple revenue streams, substantial transactions or complex expense structures, discrepancies may take time to investigate. Maintaining organized records throughout the year can help reduce delays when responding to tax notifications.
Businesses should also establish an internal process for reviewing FBR communications, assigning responsibility for responses and meeting applicable deadlines.
The broader direction is towards greater use of data analysis and electronic tax administration. Taxpayers who maintain accurate records and address discrepancies promptly will be better positioned to manage this changing compliance environment.
Role of Professional Tax Advisory Services
Responding to an FBR notification may require more than a simple explanation. Depending on the issue, taxpayers may need to review the relevant provisions of tax law, reconcile financial records, prepare supporting documentation and assess the appropriate response.
Xact Legal assists individuals and businesses with tax compliance, income tax return filing, tax documentation and guidance on tax-related matters in Pakistan.
Professional support can help taxpayers understand the issues raised, organize the required evidence and prepare appropriate responses based on their circumstances and the applicable law.
If you receive an FBR notice or identify discrepancies in your tax return, addressing the matter promptly can help you avoid unnecessary complications.
Conclusion
The FBR’s proposed automated income tax scrutiny mechanism represents a further step towards technology-driven tax administration in Pakistan. Under the proposed Rule 38B, the system would identify potential discrepancies, notify taxpayers electronically and provide a minimum seven-day response period, followed by a reminder offering at least another seven days if no response is received.
Although the proposal is intended to provide an opportunity to clarify or correct issues before formal action is considered, taxpayers should remain attentive to official notifications and comply with applicable legal requirements.
Maintaining accurate records, monitoring IRIS and seeking professional advice where necessary can help individuals and businesses manage tax scrutiny more effectively.
Need assistance with income tax compliance or an FBR notice? Contact Xact Legal for professional tax and legal support in Pakistan.