

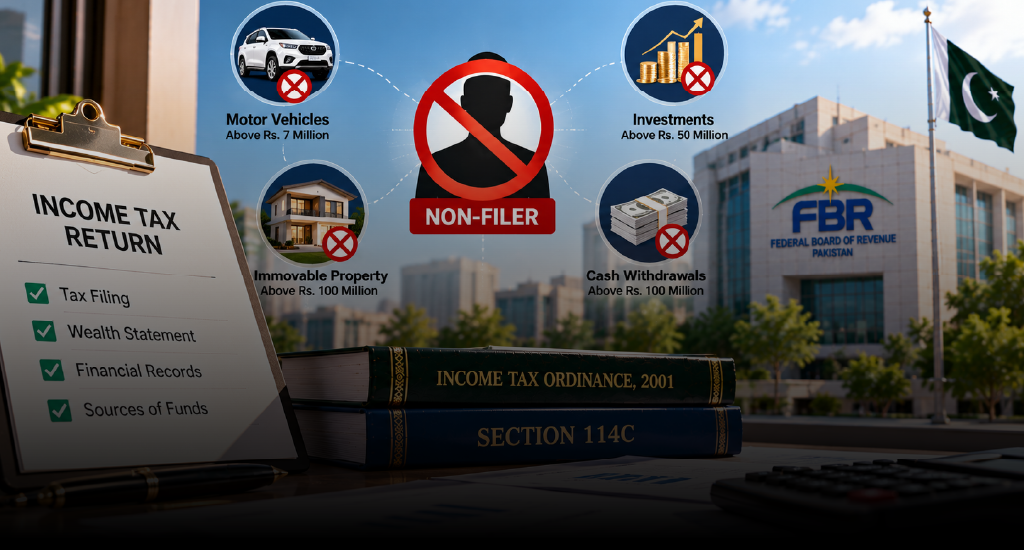
The Federal Board of Revenue (FBR) has introduced Section 114C of the Income Tax Ordinance, 2001, establishing restrictions on certain high-value transactions by individuals who do not qualify as eligible persons.
For Tax Year 2027, taxpayers should understand how Section 114C works, which transactions may be restricted, and why maintaining updated tax records is important.
What Is Section 114C?
Section 114C establishes a framework under which certain persons may be classified as eligible or ineligible based on their tax filing status and declared financial resources.
Ineligible persons may face restrictions on specified high-value financial transactions.
Transactions Covered Under Section 114C
The framework covers certain major transactions, including:
- Motor vehicles with an invoice value exceeding Rs. 7 million
- Immovable property with a fair market value exceeding Rs. 100 million
- Investments in securities, mutual funds and specified instruments exceeding Rs. 50 million
- Cash withdrawals exceeding Rs. 100 million from a bank account
The prescribed thresholds may be subject to changes under the applicable law and notifications.
Who Can Qualify as an Eligible Person?
Generally, an eligible person is required to have:
- Filed the relevant income tax return
- Submitted the required wealth statement or financial information
- Demonstrated sufficient financial resources for the relevant transaction
- Properly disclosed assets, investments and sources of funds
The rules also provide a mechanism for determining sufficient resources based on specified cash and cash-equivalent assets.
Are Section 114C Restrictions Already Effective?
An important point for taxpayers is that the restrictions under Section 114C do not automatically become operational simply because the provision exists in the law.
The Federal Government is required to appoint the effective date through notification in the official Gazette.
Taxpayers should therefore distinguish between the existence of the legal provision and its actual implementation.
What Should Taxpayers Do?
Individuals planning significant financial transactions should:
- File income tax returns within the prescribed deadlines.
- Keep wealth statements accurate and updated.
- Properly document sources of income and funds.
- Ensure major assets and investments are disclosed.
- Review their tax position before undertaking high-value transactions.
- Monitor FBR notifications regarding Section 114C implementation.
Xact Legal – Tax Compliance & Advisory
Section 114C highlights the growing importance of tax filing, wealth documentation and financial transparency in Pakistan.
At Xact Legal, we assist individuals and businesses with income tax return filing, wealth statements, tax compliance and professional tax advisory services.
Need assistance with your tax compliance or high-value transaction? Contact Xact Legal for professional tax guidance.