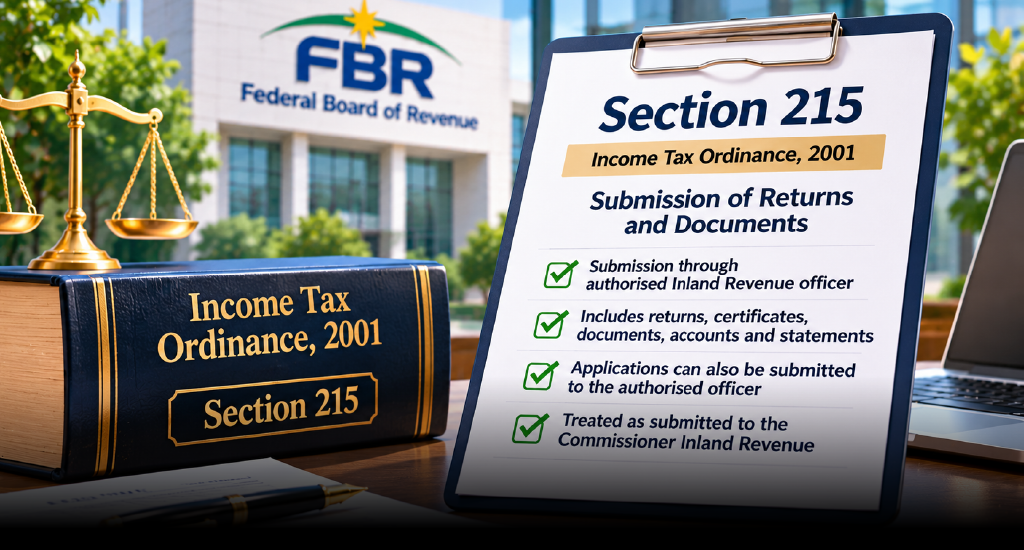
The Federal Board of Revenue (FBR) has clarified the rules for submitting income tax returns, documents and applications under Section 215 of the Income Tax Ordinance, 2001, for Tax Year 2027.
The provision explains when documents submitted to an authorised Inland Revenue officer are legally treated as having been submitted to the Commissioner Inland Revenue.
What Does Section 215 of the Income Tax Ordinance Cover?
Section 215 establishes the legal validity of certain submissions made to authorised Inland Revenue officers when the Commissioner has delegated the relevant powers under Section 210.
The provision covers two main areas:
- Submission of tax documents: Where authority has been delegated, returns, certificates, documents, accounts and statements submitted to the designated Inland Revenue officer are treated as furnished to the Commissioner.
- Submission of applications: Applications submitted to an officer authorised to receive them are treated as applications made to the Commissioner.
These provisions help establish the legal status of submissions made through officers exercising properly delegated authority.
What Should Taxpayers Know?
Taxpayers should ensure that their tax returns, supporting documents and applications are submitted to the appropriate authorised officer and in accordance with the applicable requirements.
Businesses and individuals should also retain submission acknowledgements and supporting records. Keeping accurate documentation can help resolve questions about whether a required filing or application was properly submitted.
Section 215 does not remove the need to comply with applicable filing deadlines, documentation requirements or other obligations under the Income Tax Ordinance, 2001.
How Xact Legal Can Help
Xact Legal provides tax and legal advisory services to individuals and businesses in Pakistan. Our team can assist with income tax compliance, reviewing filing requirements, organising supporting documentation and understanding relevant provisions of the Income Tax Ordinance, 2001.
Professional guidance can help taxpayers address compliance concerns and manage their tax obligations with greater confidence.
Frequently Asked Questions
What is Section 215 of the Income Tax Ordinance, 2001?
Section 215 explains when returns, documents and applications submitted to an authorised Inland Revenue officer are treated as submitted to the Commissioner Inland Revenue.
Can an authorised Inland Revenue officer receive tax documents?
Yes. Where the Commissioner has delegated the relevant powers under Section 210, the authorised officer may receive specified tax documents and applications.
Does Section 215 change income tax filing deadlines?
No. The provision addresses the legal status of submissions made to authorised officers. Taxpayers must continue to follow the applicable filing deadlines and requirements.
Conclusion
Section 215 provides a legal framework for submitting tax returns, documents and applications through authorised Inland Revenue officers. Taxpayers should verify that their submissions reach the appropriate officer and maintain records to support compliance with applicable tax requirements.
Disclaimer: This article is for general informational purposes only and does not constitute legal or tax advice. Taxpayers should consult the applicable legislation and seek professional advice for their specific circumstances.