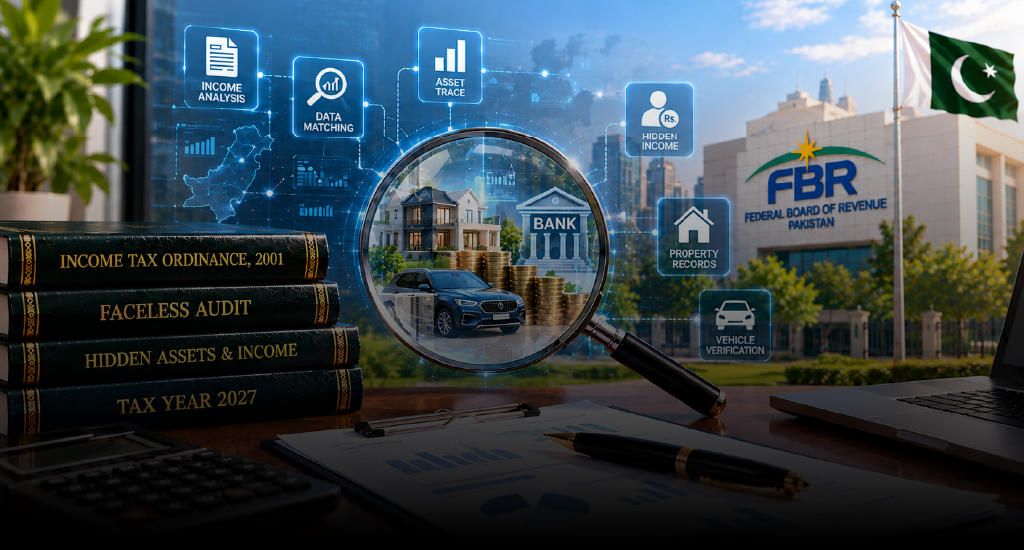
The Federal Board of Revenue (FBR) has introduced a faceless audit and assessment framework for cases involving undisclosed income and assets in Pakistan. The new system brings proceedings under Section 111 of the Income Tax Ordinance, 2001 within the National Faceless Centre framework.
Under SRO 1665(I)/2026, FBR has inserted Chapter XX into the Income Tax Rules, 2002, establishing procedures for conducting specified audits, assessments and related proceedings electronically.
Hidden Assets and Income Under Faceless Audit
The new framework covers cases involving unexplained income and assets, including proceedings under Section 111. It also provides for faceless audits under Sections 177 and 214C and assessments or amendments to assessments under the Income Tax Ordinance.
This means cases involving potentially undisclosed assets or income can be processed through a structured digital system rather than being handled solely through traditional taxpayer-officer interaction.
National Faceless Centre
The National Faceless Centre consists of four main wings:
- Audit Wing
- Assessment Wing
- Quality Control Wing
- Field Operations Wing
An FBR-designed algorithm allocates responsibilities among different officers or units. Audit, assessment and quality-control functions are separated, meaning the same officer cannot perform multiple functions for the same case and tax year.
Digital Communication Through IRIS
Under the framework, notices, orders, audit reports and other communications generated by the Centre must be issued through FBR’s computerised system and carry a Digital Identification Number (DIN).
Taxpayers and authorised representatives are required to submit replies, documents and evidence electronically through their designated IRIS accounts. Additional information, third-party data and technical expertise may also be requested during an audit.
Physical Verification Can Still Take Place
Faceless proceedings do not completely eliminate physical verification.
Where necessary, FBR may verify businesses, assets, investments, expenditure or other relevant matters through the Field Operations Wing. Cases can also be transferred where faceless proceedings are impractical because of extensive physical records, repeated verification, search and seizure proceedings or related cases.
What Taxpayers Should Do
Businesses and individuals should ensure that their income, assets and wealth statements are properly documented and consistently reported.
Taxpayers should maintain:
- Complete income and financial records
- Proper documentation for assets and investments
- Supporting evidence for sources of funds
- Accurate wealth statements
- Digital records for transactions and expenses
- Timely responses to FBR notices through IRIS
FBR has also been using data analysis to identify discrepancies between declared wealth and information available in its databases.
Xact Legal – Tax Advisory & Compliance
Xact Legal provides professional tax advisory, compliance and audit support services in Pakistan, helping individuals and businesses manage tax records, respond to FBR proceedings and maintain proper documentation for income and assets.