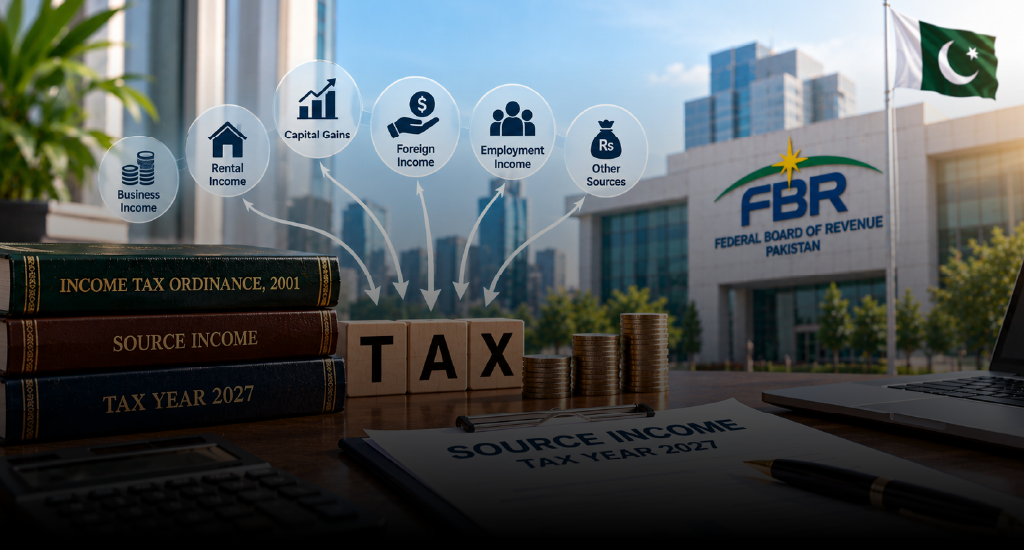
The Federal Board of Revenue (FBR) has outlined the rules for determining whether income is treated as Pakistan-source income or foreign-source income for Tax Year 2027 under Section 101 of the Income Tax Ordinance, 2001.
These rules are particularly relevant for individuals and businesses with cross-border income, foreign investments, overseas operations or digital transactions.
What Is Pakistan-Source Income?
Under Section 101, income may be treated as Pakistan-source based on where the underlying employment, business, property, payment or economic activity is connected.
Key categories include:
- Salary: Income relating to employment exercised in Pakistan.
- Business income: Income from business carried on in Pakistan.
- Rental income: Income from immovable property located in Pakistan.
- Dividends: Dividends paid by a resident company.
- Profit on debt: Certain profit on debt paid by a resident person.
- Royalties: Certain royalties paid by a resident person.
- Technical fees: Certain technical fees paid by a resident person.
- Digital services: Certain offshore digital service fees paid by a resident person.
- Capital gains: Gains from the disposal of shares in a resident company and certain Pakistan-based property.
- Pensions and annuities: Certain amounts paid by resident persons or borne by a Pakistani permanent establishment.
Rules for Non-Resident Businesses
For a non-resident person, business income may be treated as Pakistan-source to the extent it is attributable to a permanent establishment in Pakistan or a business connection in Pakistan.
Section 101 also covers certain sales, business activities and import arrangements connected with Pakistan.
Significant Economic Presence
Pakistan’s tax framework also considers significant economic presence (SEP) when determining a business connection.
This can include certain transactions involving goods, services, property, data or software with persons in Pakistan, as well as systematic and continuous digital engagement with users in Pakistan, where prescribed thresholds are met.
Pakistan-Source vs Foreign-Source Income
Section 101 provides that income which does not qualify as Pakistan-source income is treated as foreign-source income to the relevant extent.
This distinction can be important when determining the tax treatment of income earned by resident and non-resident taxpayers with international activities.
Why These Rules Matter for Tax Year 2027
The source-of-income rules are particularly relevant to taxpayers involved in:
- International business and trade
- Remote and digital services
- Foreign investments
- Overseas employment
- Rental property in Pakistan
- Cross-border payments
- Royalties and technical services
Correctly determining the source of income can help taxpayers apply the relevant provisions of Pakistan’s income tax law.
Xact Legal – Tax Compliance Support
Determining whether income is Pakistan-source or foreign-source can become complex when transactions involve multiple countries or digital business models.
Xact Legal provides professional tax, corporate and legal services in Pakistan, helping individuals and businesses understand their tax obligations and maintain compliance with applicable laws.
Need assistance with Pakistan-source income or Tax Year 2027 compliance? Contact Xact Legal for professional guidance.