

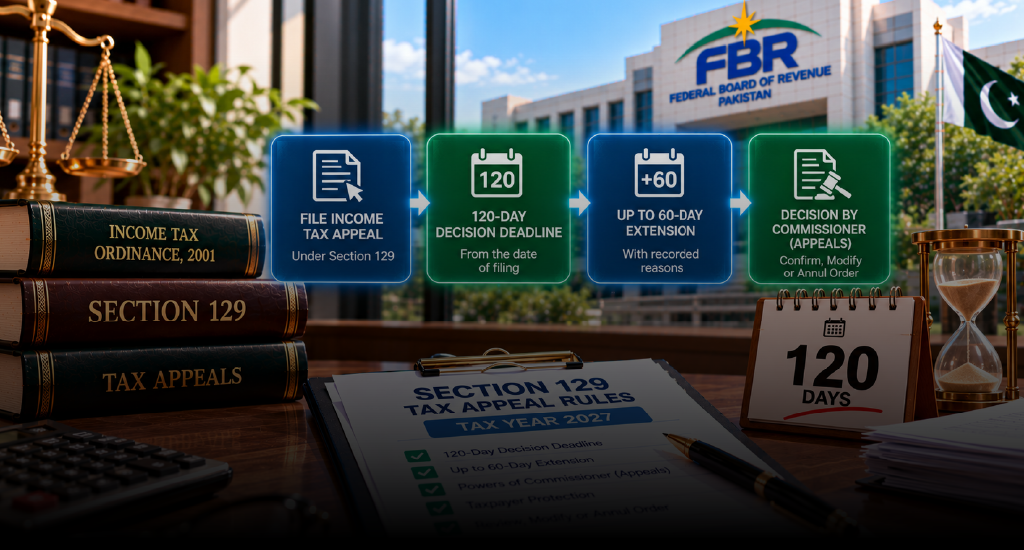
The Federal Board of Revenue (FBR) has outlined the timeline for deciding income tax appeals under Section 129 of the Income Tax Ordinance, 2001, for Tax Year 2027. The provision sets a general deadline of 120 days for the Commissioner (Appeals) to decide an appeal, with an extension of up to 60 additional days in specified circumstances.
What Is Section 129 of the Income Tax Ordinance?
Section 129 explains the powers of the Commissioner (Appeals) when deciding appeals filed against eligible income tax orders. It provides a legal framework for reviewing assessment decisions, examining evidence, and determining whether an order should be confirmed, modified, or annulled.
The provision aims to ensure that tax disputes are handled through a defined appellate process.
120-Day Deadline for Deciding Tax Appeals
Under Section 129, the Commissioner (Appeals) is generally required to decide an appeal within 120 days from the date it is filed.
The law also permits an extension of up to 60 additional days, provided the reasons for the extension are recorded in writing.
Certain periods may be excluded when calculating the deadline. These can include delays resulting from adjournments requested by the appellant, stay orders, remand proceedings, alternative dispute resolution proceedings, and other circumstances specified under the law.
Powers of the Commissioner (Appeals)
While deciding an income tax appeal, the Commissioner (Appeals) may:
- Confirm the original assessment order.
- Modify the assessment based on the case and available evidence.
- Annul the assessment order.
- Examine relevant evidence or direct further inquiries.
- Issue an appropriate order in other appealable matters.
These powers allow the appellate authority to review the disputed tax matter and reach a decision in accordance with the applicable law.
Protection for Taxpayers Against Adverse Changes
Section 129 also provides an important procedural safeguard. The Commissioner (Appeals) cannot increase a taxpayer’s assessment or reduce a refund without giving the taxpayer a reasonable opportunity to explain why the proposed change should not be made.
This requirement helps ensure that taxpayers have an opportunity to present their position before an adverse decision is issued.
Why the 120-Day Tax Appeal Deadline Matters
The statutory timeline provides greater clarity for taxpayers awaiting decisions on income tax appeals. However, the actual time taken may depend on the circumstances of the case and any periods excluded under the law.
Taxpayers should maintain complete documentation, monitor their appeal proceedings, and seek professional guidance when dealing with disputed assessments or refund matters.
How Xact Legal Can Help
Xact Legal provides tax and legal advisory services to individuals and businesses in Pakistan. Our team can help taxpayers understand appeal procedures, assess tax disputes, organise relevant documentation, and navigate applicable compliance requirements.
Contact Xact Legal for professional guidance on income tax appeals, assessment disputes, and tax compliance matters.